
BUSINESS
Saible Puts £2.9m on a Digital Project Bank Account
Saible raised £2.9m to pay every construction tier at once after project bank accounts stalled and an unused account failed in court.

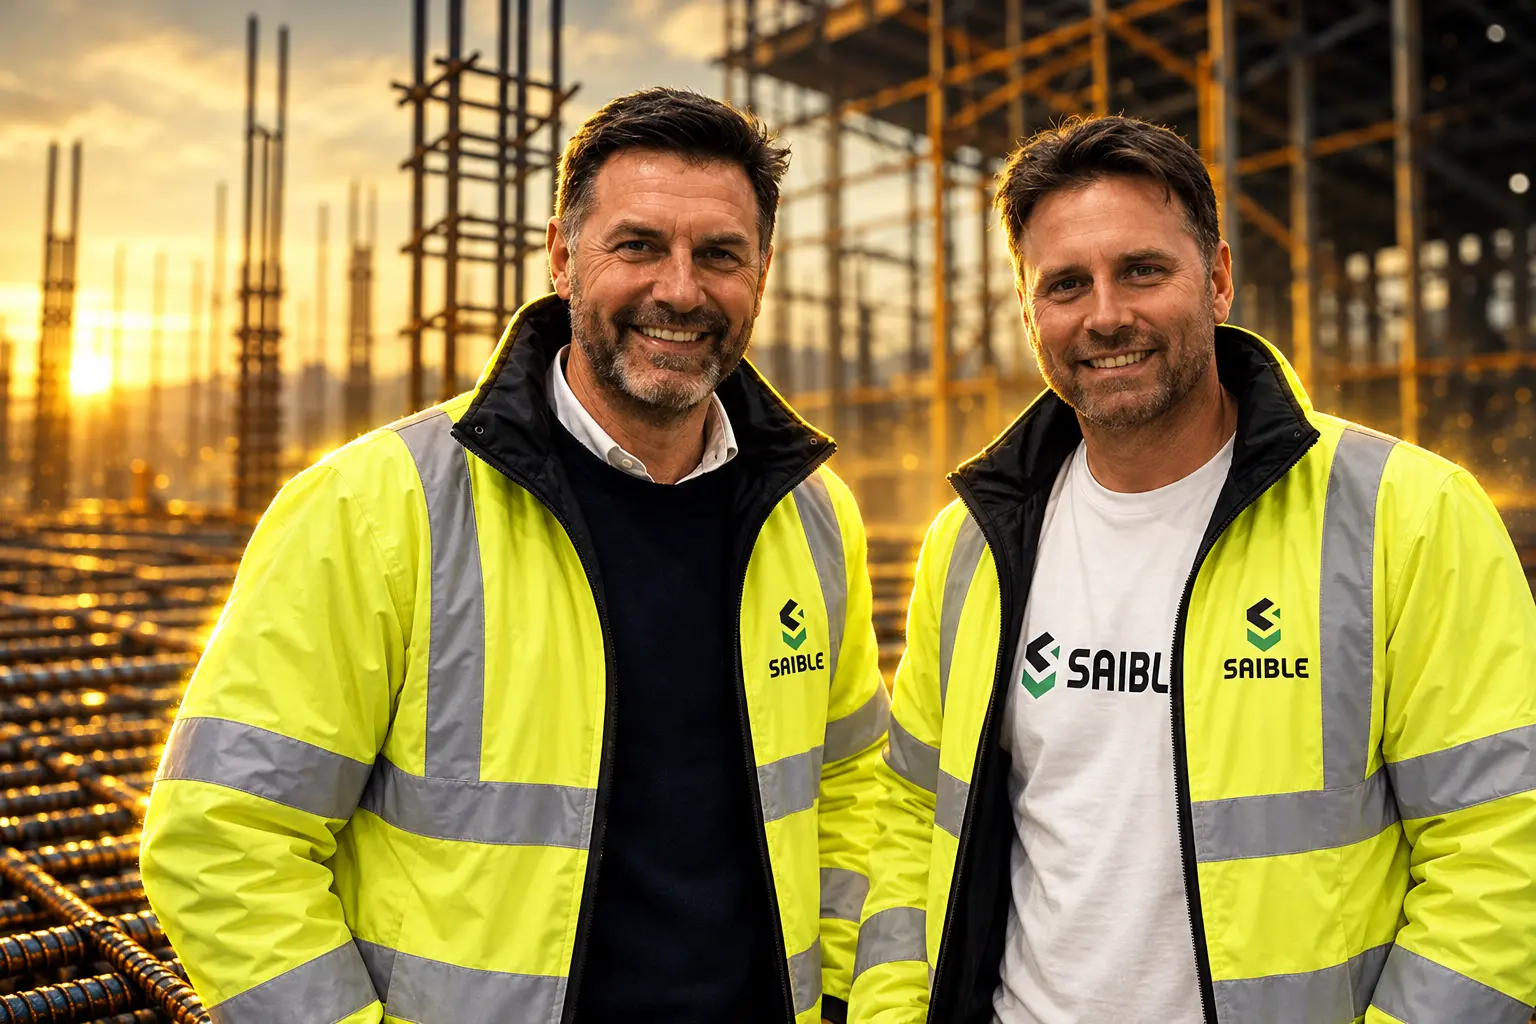
Birmingham fintech Saible has raised £2.9m from angels to pay every tier on a construction job at once. The money is a £2.1m pot already in plus a further £800,000. Project cash sits in a trust at digital bank Griffin and is meant to leave that account to approved firms together, not drip from contractor to subcontractor.
That is the same job Whitehall gave project bank accounts more than a decade ago. Those accounts stayed rare, and in August 2026 a High Court case showed what happens when the paperwork is signed and the account is never opened.
Angels Put £2.9m Behind Simultaneous Pay
Saible sells a Digital Parallel Payment Account, or DiPPA. The project owner pays a 0.25 per cent fee on the payment value. The supply chain pays nothing. Approvals, checks and the audit trail sit in Saible’s software. Griffin holds the deposits and sends the money.
Co-founder and chief executive Jarvey Moss said payment in construction is “dysfunctional and is in desperate need of better control.” The raise, he said, is for the platform, talks with regulators, and more live jobs with project funders who want a clearer view of how cash moves.
Moss started as a musician and tour manager, then co-founded Amigo Technology in 2014 and left in 2022. Dr Tim Whitehill, the chief strategy officer, had run a specialist civil engineering firm and later a consultancy on how contractors work. They met at UKREiiF, founded Saible Ltd in September 2023, and launched DiPPA in January 2025. The firm says it is already taking revenue.
With the angel money came a limited £50,000 Crowdcube slice aimed at smaller construction firms and people in the trade. The public round was opened in mid-July 2026. How much of that slice filled has not been published.
On a large job, up to five tiers can sit between the client and the smallest supplier. At each step the firm holding the cash can park it as free credit. Moss is selling the opposite: the owner funds a trust, each tier still signs off its own subcontractors, and Griffin pays everyone who is approved at the same time.
The Playbook Account That Stayed Optional
Project bank accounts were built to stop that parking. Money for a job goes into a ring-fenced account. Named suppliers are paid from it. If the main contractor fails, the cash in the account is not supposed to vanish into the insolvency estate. Moss has written that where they are used with discipline, as at National Highways and the Environment Agency, they have generally done the work.
Use was never broad. Public clients have been told since 2010 to apply them unless there are compelling reasons not to. Most private clients have barely heard of them. High street banks, Moss said, dislike the trust structure and the fact the balance does not sit long enough to lend against.
HOW PROJECT BANK ACCOUNTS STALLED
- 2012: The Cabinet Office publishes project bank account guidance so named suppliers can be paid from ring-fenced job cash.
- 2018: Carillion collapses and leaves about £2 billion of damage in the supply chain.
- 2020: The Construction Playbook tells public clients to use the accounts unless there are compelling reasons not to.
- 2023: Freedom of Information figures show nine of 80 major justice, defence and health contracts let from 1 January 2022 used a project bank account, and the Department for Education said it did not use them on school capital jobs.
- August 2025: The Cabinet Office marks its own guidance out of date and says a replacement is being prepared.
- August 2026: The High Court dismisses a subcontractor’s claim on a Vale of Glamorgan school job where the account was never opened.
Wales already requires the accounts on public construction above £2m. Scotland requires them on building jobs above £2m and civil engineering above £5m. Whitehall never made the same rule stick. Moss’s own list of faults is blunt: they can take months to open, they need witnessed wet-ink signatures on trust deeds, they add admin for the people running them, they can leak commercial numbers, and they pinch cash for firms at the top of the chain who are used to holding other people’s money.
Think of a DiPPA as a PBA updated for the smartphone era. Under the hood lies a PBA, but the overlying technology addresses the weak points of a traditional PBA, retaining its benefits, and adding some new ones on top.
Jarvey Moss, co-founder and chief executive of Saible, Construction Industry Council
A School Job in Penarth Showed the Gap
The warning did not come from a fintech deck. It came from a school extension in Penarth. In August 2023 the Vale of Glamorgan Council hired ISG on an amended NEC4 contract. Works began in April 2024. In May 2024 ISG hired E & TL Jones as groundworks subcontractor, again on an NEC4 form.
The main contract used NEC Option Y(UK)1 from 2017, which required ISG to set up a project bank account and the council to pay into it. The trust deed was signed by ISG and the council. Jones was never added. In the event, no project bank account was ever established.
The council then paid ISG direct, including sums tied to Jones’s work. The last of those payments never reached Jones before ISG went into administration in September 2024. Jones sued the council as a third party under the Contracts (Rights of Third Parties) Act 1999. The High Court dismissed the claim in August 2026 ([2026] EWHC 2054 (TCC)). Jones was not a Named Supplier. The judge also held that the council’s duty to pay into the account could only arise once the account existed, and that until then the council had to pay ISG to meet its other payment duties.
ISG’s wider collapse left creditors looking at about £1.1 billion. The Penarth file is smaller and colder. A tool that only works if someone bothers to open the account is not a tool when the contractor that was meant to open it is the one that fails.
How a DiPPA Splits Cash From Sign-Off
Saible’s pitch is that authorisation can still run down the contract chain while the cash does not. The client pays the trust. Each firm still signs off the tier below. Griffin then pays every approved party from the same account in one pass. Contracts stay as they are. Lower-tier firms do not wait for the company above them to pass the money on.
Saible Ltd is not a bank, does not hold client money, and does not fire the payments. Griffin Bank Limited is a UK bank authorised by the Prudential Regulation Authority and regulated by the PRA and the Financial Conduct Authority, firm reference number 970920 on Griffin’s entry on the Financial Services Register. When a user asks for a payment, Griffin sends it from the account.
Moss has said traditional accounts are hard to set up and slow to open. Due diligence and the trust deed are meant to be done once at onboarding, then reused. Saible prefers the client as sole trustee. On the Environment Agency trials the contractor and client are joint trustees. A named trustee still watches the trust agreement; the bank still holds the cash, so an insolvency of the contractor is not supposed to freeze or redirect it.
PBA VERSUS DIPPA ON THE POINTS THAT MATTER
| Point | Project bank account | DiPPA |
|---|---|---|
| Who holds the cash | A ring-fenced account, often with a high street bank | A trust account at Griffin |
| Who gets paid, and when | Named suppliers, if they have been added and the account exists | Approved firms across tiers, in one release |
| Who signs off | Often the client or main contractor as trustee, which can bottleneck | Each tier signs off its own subcontractors |
| Setup | Can take months, with witnessed signatures on each job | Trust work done at onboarding and reused |
| Fee | Admin load, no standard public tariff | 0.25 per cent, paid by the project owner |
| If the contractor fails | Protects named parties only when the account was actually opened | Job funds sit in trust, not as the contractor’s asset |
That last row is the whole Penarth problem restated as a product choice. Saible also sells a layer that sits on an old-style project bank account, plus a retention trust account, which is a tell. The company is not only trying to retire the analogue version. It is selling plumbing for the version the Playbook already asked for and for the retention cash that Parliament now wants to kill.
Griffin recorded Moss in late 2025 on what the first live job had shown and what the public pilots were for.
3,866 Insolvencies Follow the Cash
Late payment is not a mood. Insolvency Service figures recorded 4,032 construction insolvencies in 2024, 17 per cent of cases where an industry was captured, the largest of any sector. In the 12 months to August 2026 the same service counted 3,866 construction insolvencies, still 17 per cent of the total and still the top sector. That 12-month tally was about 2 per cent lower than the year to August 2025 and still 20 per cent above 2019.
CONSTRUCTION FAILURES ON THE OFFICIAL COUNT
- Calendar 2024: 4,032 insolvencies, 17 per cent of cases with an industry recorded.
- Year to August 2026: 3,866 insolvencies, again 17 per cent, still the largest sector.
- August 2026: 294 insolvencies in the month, 164 of them in specialised trades, more than half.
- Relative to 2019: the latest 12-month total sits 20 per cent above the pre-pandemic year.
Specialist trades (the electricians, groundworkers, plumbers, plasterers) take the hit first because they sit furthest from the client and closest to payroll. Accountancy firm Menzies, in a Censuswide survey of 250 senior finance people in construction and property published in June 2026, found 93 per cent reporting late payment, on average 53 days overdue. Some 86 per cent said they were in or near serious distress, with the average firm eight months from that point, and 20 per cent said they were funding the job themselves while they waited.
A September 2026 survey of 127 UK subcontractor firms by payment software company Payapps found 79 per cent almost always paid late and 73 per cent regularly in disputes over applications. Sixty-eight per cent had raised rates or added a risk margin because payment was slow or unreliable. Delay is already in the bid. Main contractors who treat supply-chain cash as a working-capital line are paying for it in the price of the next trade, even when they still win the argument on the month’s application.
Moss has put the industry’s own late and non-payment bill at around £6 billion a year. The Department for Business and Trade has put late payment across the whole economy at £11 billion a year. Those are different bases. Both point the same way for a small contractor waiting on a named sum.
Retentions Face a Ban Before the Accounts Catch Up
While Saible raises private cash for a better account, Parliament is trying to ban the other cash trap. On 24 March 2026 the Department for Business and Trade said it would prohibit retention clauses in construction contracts, cap payment terms, and put statutory interest on late sums. The Commercial Payments Bill has since carried that package. Report stage in the House of Lords finished on 15 September 2026. Third reading is listed for 20 October 2026.
WHAT THE BILL WOULD CHANGE
- Retentions: a ban on deducting and holding retention under construction contracts, after a two-year transition, with a later hard stop when leftover clauses become void.
- Public jobs: a 30-day maximum payment period where the payer is a public authority.
- Private jobs: a 60-day maximum, with longer contract terms treated as void.
- Interest: statutory interest at 8 per cent over Bank of England base on late commercial debts, harder to contract out of.
Legal notes on the bill warn that money parked with a third party as security for performance could itself be treated as a banned retention. That is not a side issue for a firm whose other product is a retention trust account. If cash cannot be held back as retention, clients will look for another way to keep leverage on defects. Bonds, escrow, and protected project accounts are the obvious substitutes. A digital account that already pays the chain in parallel is one of the few tools that does not recreate the old withhold.
That is not law yet. Commencement dates are not set. The industry still has time to rewrite standard forms, and plenty of reason to stall. The last analogue account was optional. This ban, if it survives, would not be.
Live Tests on Two Environment Agency Jobs
The public test is small on purpose. Bam Nuttall, the civil engineer, put DiPPAs on two Environment Agency contracts in the North East and East of England in late 2025, its first use on a public job. Saible billed the first of those public pilots as a footbridge replacement worth £1.5 million to £2 million, due to start in summer 2026 and run 12 to 16 months. The Cabinet Office and the National Infrastructure and Service Transformation Agency are watching. The pilots follow a Cabinet Office-sponsored group on construction payment and are meant to produce figures on visibility, timing, and how far down the chain the money actually reaches.
The first private job was a small housing scheme in Chester, finished in October 2025. Saible has said it was onboarding two more private jobs after that and expected a much larger set in 2026. A later company note still described the Environment Agency pilot as due to start in 2026, so the footbridge should not be treated as a finished case study.
JOBS ON THE RECORD
- Chester housing: first private DiPPA, completed October 2025.
- Two EA civils jobs: Bam Nuttall as contractor, North East and East of England, signed in late 2025.
- Footbridge replacement: billed at £1.5 million to £2 million, 12 to 16 months, public pilot due to start in summer 2026.
Banks and insurers have a separate reason to care. A ring-fenced trust is a cleaner picture of project cash than a main contractor’s current account, which is why lenders looking at distressed development loans sit on Saible’s other product list. The people who put the money in, not the people who have been parking it, are the customer.
That is the bet the £2.9m is paying for. Project bank accounts asked contractors to give up a float they use as working capital, then left them to open the account. Plenty never did. Saible is asking project owners to take the rail instead, at 0.25 per cent, with a bank that is built to move the balance rather than sit on it. On 20 October the Lords are due to give the retention ban its third reading. The Penarth account still was not opened.

UPI MDR Delay Hands Traders the Calendar After Paytm Falls

Google Messages Builds Nine In-Chat Games After Samsung’s Exit

Anthropic’s $100 Million Academy Trains the Firms That Bill Both Sides

Toyota’s Electric C-HR Leaves the Cheap Twin to Subaru

Markets Bet the Fed Skips October After Hawkish Minutes

The Orchard Bug Forced Zcash to Open an Empty Pool

The $5.99 Game That Won Steam’s 2026 Summer Sale

Don Lee Joins Hemsworth as Extraction 3 Starts Shooting

YouTube Shorts Retires Dislikes and Swaps Likes for Hearts

NEURA Robotics Is Spending Its $1.4B on a Machine Stack
-
 NEWS5 months ago
The Orchard Bug Forced Zcash to Open an Empty Pool
-
 GAMING5 months ago
The $5.99 Game That Won Steam’s 2026 Summer Sale
-
 ENTERTAINMENT7 months ago
Don Lee Joins Hemsworth as Extraction 3 Starts Shooting
-
 NEWS5 months ago
YouTube Shorts Retires Dislikes and Swaps Likes for Hearts
-
 NEWS4 months ago
NEURA Robotics Is Spending Its $1.4B on a Machine Stack
-
 NEWS5 months ago
Atlantic City Turned WWE’s Return Into a Civic Night
-
 AUTO6 months ago
Kawasaki Bets the New Z1100 Against Its Own Supercharger
-
 BUSINESS5 months ago
Norway’s Export Bank Backs Nscale’s $790 Million Narvik Loan