
BUSINESS
Kalshi Keeps HYPE Perps Live as CME Sues the CFTC
HYPE perpetuals still rank fourth on Kalshi three months after CFTC clearance, while CME sues to unwind the order Hyperliquid is now defending.

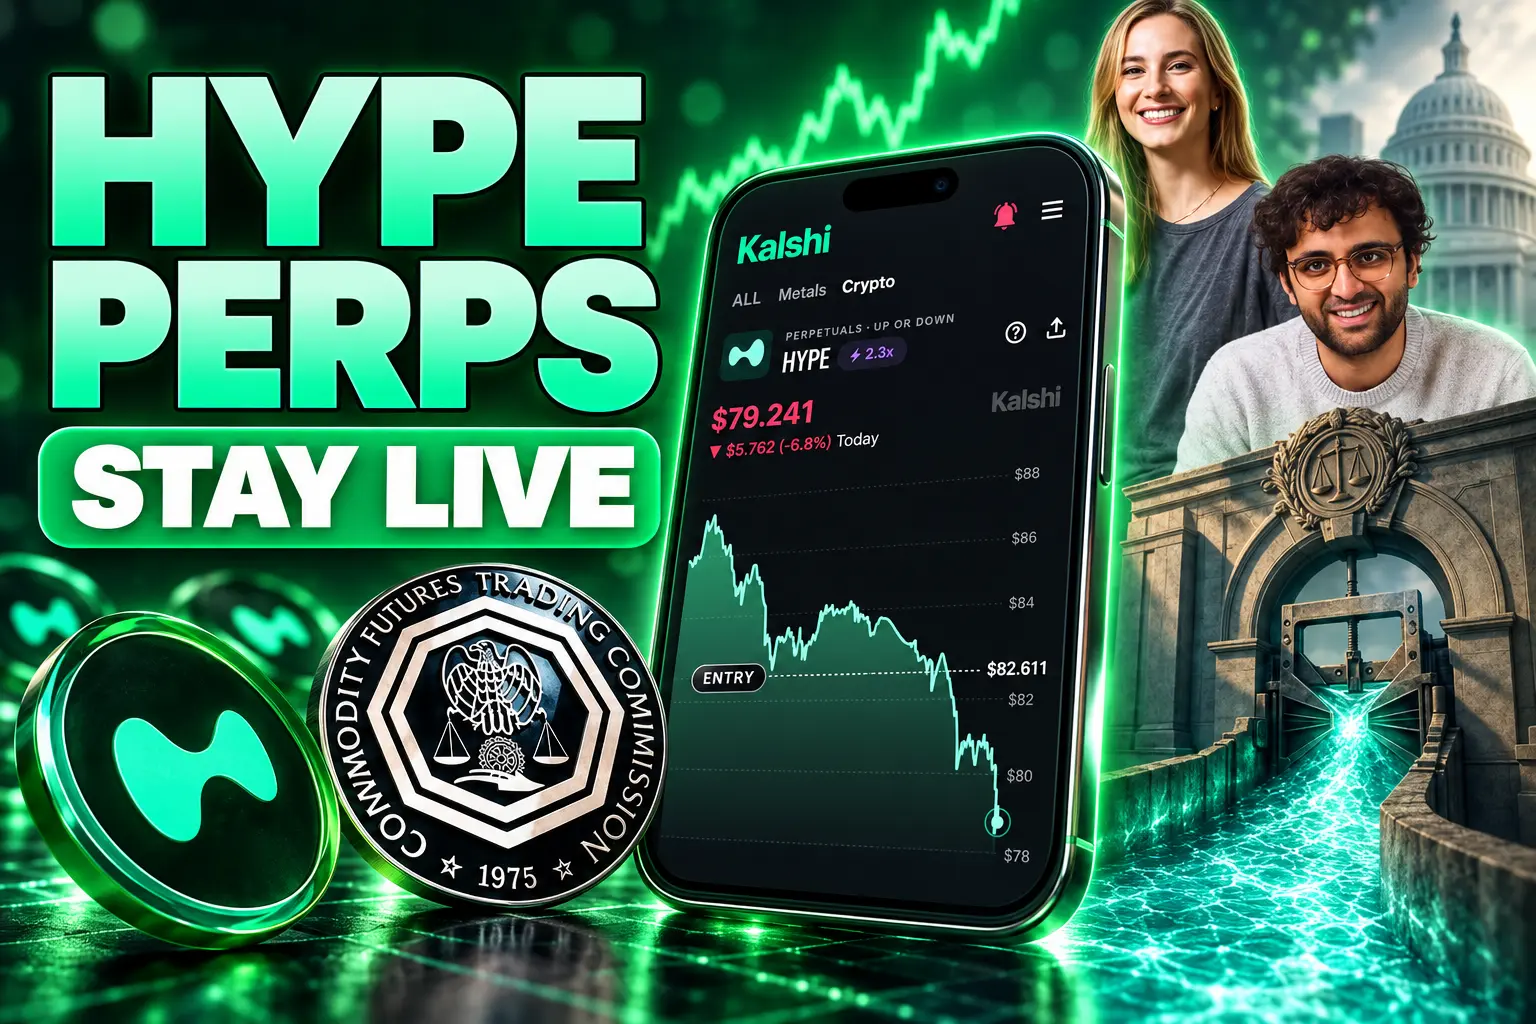
Kalshi listed Hyperliquid HYPE perpetual futures on June 11 after Commodity Futures Trading Commission clearance, and the contract still ranks fourth by volume on the venue. The HYPE perpetual changed hands at $79.039 on the September 11 tape, with $12.29 million in 24-hour volume and $2.53 million in open interest.
The listing put a CFTC-wrapped HYPE bet in front of US traders who still cannot open an account on Hyperliquid itself. That wrapper is now the live exhibit in Chicago Mercantile Exchange Inc. v. Selig, the suit asking a federal judge to unwind the May order that made the product possible.
HYPE Still Ranks Fourth on Kalshi’s Perp Board
On listing day, HYPE jumped more than 10 percent to $59.40, with an intraday high of $59.45 and a low of $52.70. Global HYPE futures open interest rose 11 percent to $2.49 billion, enough to pass XRP on that print. Kalshi waived trading fees for a limited window and skipped a waitlist.
Three months later the US book is quieter and still there. Loris Tools, a derivatives data desk, logged Kalshi’s HYPE perpetual at $79.039 as of 00:13 UTC on September 11, down 5.56 percent on the session, with a 1.80 bps funding print that annualizes to 19.71 percent. Only bitcoin, ether, and Zcash did more volume on the same board.
US traders who want levered HYPE without leaving a registered futures commission merchant are using that Kalshi contract, because the chain that issues the token still blocks them. The onshore interest is real. It is also a rounding error next to the June 11 global futures book of $2.49 billion.
A One-Day Order Built the American Perp Market
KalshiEX, LLC, the CFTC-designated contract market behind the prediction-market app, filed the BTCPERP bitcoin contract on May 28 under Commission Regulation 40.3, the voluntary pre-approval path. The Commission issued approval of the BTCPERP contract the next day, Release Number 9240-26, treating a no-expiry bitcoin perpetual as a futures contract rather than a swap.
Chairman Michael S. Selig, then the sole confirmed commissioner, signed the order under Section 5c(c)(4) of the Commodity Exchange Act. A companion policy statement, Release 9242-26, sent perpetuals on other asset classes back to case-by-case 40.3 review and warned that “the perpetual contract design may not be suitable for all asset classes.”
Having true perpetual contracts in the United States is a major step forward in delivering on President Trump’s goal of cementing America as the crypto capital of the world.
Michael S. Selig, CFTC Chairman, May 29, 2026 statement
In that same statement, Selig said permitting a true bitcoin perpetual contract on a registered exchange would keep leverage, volatility, and risk inside the US rulebook instead of pushing them offshore. Kalshi CEO Tarek Mansour said onshore perps would “improve capital allocation and risk management for countless American businesses.” Bitcoin went live on June 3, ether on June 4, XRP and Solana on June 10. Kalshi filed the HYPE contract on June 9. It was trading two days later.
HOW THE HYPE CONTRACT GOT ON THE BOARD
- February 2, 2026: Hyperliquid publishes HIP-4, the outcome-market upgrade later co-authored with Kalshi’s crypto desk.
- March 2026: Kalshi and Hyperliquid announce a partnership on on-chain prediction markets.
- May 2, 2026: HIP-4 activates on Hyperliquid mainnet.
- May 28, 2026: KalshiEX files BTCPERP under Regulation 40.3.
- May 29, 2026: The CFTC approves BTCPERP as a futures contract and issues the perpetual-contracts policy statement.
- June 3, 2026: Bitcoin perpetuals go live on Kalshi.
- June 9, 2026: Kalshi files a HYPE perpetual with the Commission.
- June 11, 2026: HYPE perpetuals begin trading for US users.
- June 18, 2026: CME sues the CFTC and Selig in the District of Columbia, case 1:26-cv-02157.
- September 2, 2026: The CFTC moves to dismiss.
- September 9, 2026: The Hyperliquid Policy Center files an amicus brief backing that motion.
- September 10, 2026: Kalshi lists gold and silver perpetuals after a separate CFTC clearance.
The HYPE listing was never a one-off altcoin stunt. It was the first DeFi-native token through a door the Commission had opened for bitcoin eight days earlier, under a review process that still treats each new underlying as its own case.
The Partnership Cuts Into Both Core Businesses
Kalshi and Hyperliquid spent the spring writing on each other’s turf. John Wang, Kalshi’s head of crypto, co-authored HIP-4, the Hyperliquid Improvement Proposal that puts fully collateralized yes/no outcome contracts on HyperCore, the same central limit order book that runs the chain’s perps and spot markets. The two firms announced a partnership in March to launch those on-chain event markets together.
HIP-4 went live on May 2 with dated binary contracts that settle to 0 or 1, share margin with perps, and settle in USDH. Opening a position is free; fees hit on close, burn, or settlement. That pricing is aimed at Polymarket and at Kalshi’s own event book, the business Kalshi was built on.
HIP-4 IN BRIEF
- The product: Fully collateralized outcome contracts that settle to 0 or 1 at expiry, with yes and no bids merged into one book.
- The engine: Same HyperCore matching stack as Hyperliquid perps and spot, so event risk can sit next to a HYPE or BTC perp in one account.
- The Kalshi tie: Wang co-authored the spec, and the March partnership was meant to put regulated prediction-market design onto a public chain.
- The catch for Americans: HIP-4 runs on Hyperliquid, which still refuses US users, so the on-chain half of the partnership is closed to the same people who can now trade HYPE on Kalshi.
Kalshi then listed a CFTC-regulated HYPE perpetual on its own designated contract market. Hyperliquid got a US price signal and a headline for its token. Kalshi got a DeFi-native underlying that no other registered US venue had listed. Each firm used the partnership to sell the product the other one is famous for.
How Small the Onshore Book Still Is
Kalshi told the market its perps took in more than $100 million of notional on day one and crossed $1 billion inside a week. The company has since put cumulative crypto-perp notional at $44 billion since late May. Loris Tools, on the September 11 snapshot, showed 20 perpetual futures markets on the venue, $747.67 million of 24-hour volume, and $27.65 million of open interest.
THE KALSHI PERP TAPE, SEPTEMBER 11
| Contract | Price | 24h volume | Open interest |
|---|---|---|---|
| BTC | $76,810 | $436.70 million | $12.01 million |
| ETH | $2,447.1 | $218.63 million | $2.59 million |
| ZEC | $1,090.4 | $14.04 million | $2.04 million |
| HYPE | $79.039 | $12.29 million | $2.53 million |
| SOL | $99.232 | $10.94 million | $1.09 million |
| XAU (gold) | $4,318.3 | $2.93 million | $1.41 million |
HYPE’s $2.53 million of open interest sits just behind ether’s $2.59 million and well ahead of Solana. Bitcoin still holds $12.01 million of the $27.65 million book. Gold, listed a day earlier, already showed $1.41 million of open interest and $2.93 million of volume. Silver printed $1.32 million of volume and $520.59 thousand of open interest on the same tape.
Kalshi’s September 10 post on gold and silver perpetuals called them the first of their kind in America and pointed to $90 trillion of offshore perp volume in 2025 as the pool it wants. The June altcoin queue has mostly arrived: dogecoin, Chainlink, bitcoin cash, litecoin, Sui, and Shiba Inu all trade on the same board. Stellar, Polkadot, and Hedera, named in the original pipeline, do not show in the top 20.
The honest read of that tape is that Kalshi built a regulated US perp menu, HYPE earned a real seat on it, and the whole onshore book would not fill a busy hour on Hyperliquid. That gap is the point of the listing. It is a legal product, not a liquidity venue.
CME’s Lawsuit Treats Perps as Swaps
Seven days after HYPE went live, Chicago Mercantile Exchange Inc. sued the CFTC and Chairman Selig in the US District Court for the District of Columbia. The CME complaint in D.C. court, case 1:26-cv-02157, assigned to Judge Colleen Kollar-Kotelly, asks the court to vacate the May 29 BTCPERP order and the policy statement that let other digital-commodity perps follow.
CME’s filing says perpetual contracts are swaps under the Commodity Exchange Act as amended by Dodd-Frank, because they exchange periodic payments on the value of a commodity, never expire, and never deliver. A futures contract, CME argues, is a “contract of sale of a commodity for future delivery.” The complaint says Selig “overrode Congress’s definition of the term ‘swap’” in one day, without notice-and-comment rulemaking, and reversed prior CFTC enforcement that treated offshore perps as swaps.
CME Group chief Terrence Duffy had already called perpetual futures a “disaster waiting to happen” and said they belong under the swap regime. The CFTC has called the suit frivolous. On September 2 the agency moved to dismiss for lack of jurisdiction and failure to state a claim. If CME wins, the HYPE contract, the gold and silver prints, and every other American perp on Kalshi sit on an order a court has been asked to tear up.
Former Solicitor General Prelogar Backs Kalshi’s Order
The Hyperliquid Policy Center, the token’s Washington shop, entered that case on September 9. Represented by former Solicitor General Elizabeth Prelogar at Cooley LLP, HPC filed an amicus brief urging the court to grant the CFTC’s motion to dismiss. The brief argues CME has no Article III injury because the May order enlarged the market rather than splitting a fixed one, and that Kalshi has been a designated contract market since 2020, so no new competitor was created.
HPC also argues CME’s interest in blocking a product it chose not to list falls outside the Commodity Exchange Act’s zone of interests, which include responsible innovation and fair competition among exchanges. The center’s public statement put the commercial point in plain language.
— Hyperliquid Policy Center (@HyperliquidPC) September 9, 2026
HPC said CME’s lawsuit “is an attempt to halt innovation in the U.S. futures markets,” and that “U.S. leadership in global finance depends on the CFTC’s ability to approve products without CME’s permission.” The same statement flags the next fight: on-chain markets that trade, clear, and settle on public blockchains such as Hyperliquid. That is why a venue that still bans Americans is paying a former solicitor general to defend Kalshi’s bitcoin order. The order is the template. HYPE on Kalshi is the first non-major token through it.
US Traders Get HYPE Exposure Without Hyperliquid Access
Hyperliquid still will not onboard US users. In July the Policy Center and Phantom asked the CFTC to treat software developers as something other than exchanges and to let registered firms use blockchains for matching, margin, clearing, and settlement. On August 19, President Donald Trump said Chairman Selig “is working to bring Hyperliquid into the United States in a fully compliant and legal fashion.” No order, no date, and no US user flag has followed.
What Americans actually have is the Kalshi contract: USD-margined, no expiry, CFTC-supervised, fourth on the board, $2.53 million of open interest. What they do not have is Hyperliquid’s book, HIP-4 outcome markets, or unified margin with the chain’s other perps. CME wants even that thin onshore product declared a swap and taken down. Hyperliquid wants the futures label to survive so a later on-chain version can wear it.
The June 11 listing did what a listing can do. It put HYPE on a registered US futures exchange, left the actual Hyperliquid venue offshore, and handed both firms a shared legal problem in Judge Kollar-Kotelly’s courtroom. The contract is still live. The exchange behind the token is not.
Disclaimer: This article is news reporting and analysis of a listed derivatives product and a pending federal case, and it is for information only. It is not investment advice, trading advice, or legal advice, and it does not recommend buying, selling, or holding HYPE, trading Kalshi or Hyperliquid perpetuals, or taking any position in CME Group or related securities. Readers should consult a licensed financial adviser and, for questions about the lawsuit or contract status, a qualified attorney before acting. Prices, open interest, listings, and docket entries reflect the cited sources as of the dates named in the piece and can change with the next session or filing.

Copilot Capital Buys the Autopilot Already Running 90 GW

Walmart Puts Dunkin on the App to Sell More Groceries

Molten Bets £100m of Plc Cash on Late-Stage Tech

Ascentiz Recruits Developers Around Its Modular Exoskeleton at IFA

BIS Puts a Public Timestamp Under Official Statistics on XRPL

The Orchard Bug Forced Zcash to Open an Empty Pool

The $5.99 Game That Won Steam’s 2026 Summer Sale

Don Lee Joins Hemsworth as Extraction 3 Starts Shooting

YouTube Shorts Retires Dislikes and Swaps Likes for Hearts

NEURA Robotics Is Spending Its $1.4B on a Machine Stack
-
 NEWS4 months ago
The Orchard Bug Forced Zcash to Open an Empty Pool
-
 GAMING4 months ago
The $5.99 Game That Won Steam’s 2026 Summer Sale
-
 ENTERTAINMENT5 months ago
Don Lee Joins Hemsworth as Extraction 3 Starts Shooting
-
 NEWS3 months ago
YouTube Shorts Retires Dislikes and Swaps Likes for Hearts
-
 NEWS3 months ago
NEURA Robotics Is Spending Its $1.4B on a Machine Stack
-
 AUTO5 months ago
Kawasaki Bets the New Z1100 Against Its Own Supercharger
-
 BUSINESS4 months ago
Norway’s Export Bank Backs Nscale’s $790 Million Narvik Loan
-
 AUTO5 months ago
The Kawasaki Z1100 Awakens Sugomi With Less Peak Power